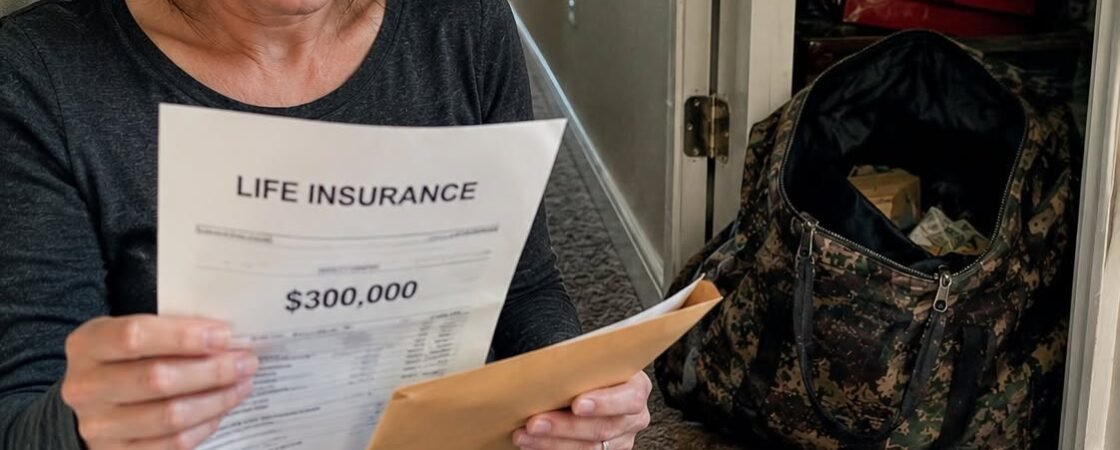
My husband forged my signature on a $300,000 life insurance policy. He named his secretary as the sole beneficiary and kept paying premiums with our grocery money for 9 years. I found the paperwork while cleaning his hunting bag. Then the insurance investigator asked me one question that made his blood freeze.
It’s still hard for me to tell this without my hands shaking.
I had been married to Dale for 14 years. We lived in a quiet house on Birchwood Lane, just outside Louisville. Two kids — Emma, 11, and Jack, 8 — a golden retriever named Biscuit, and a garden I kept up on weekends. From the outside, we looked like any other family on our street.
But for the last 3 years, things had been quietly falling apart.
The grocery budget kept shrinking. Dale said it was the economy. He said business was slow at the dealership where he managed the service department. He said we needed to tighten up. So I started buying store brand everything. I clipped coupons from the Sunday paper. I skipped my own doctor appointments to keep the kids covered on the family plan.
Meanwhile, Dale never missed a single hunting trip. New boots every season. A brand new Vortex rifle scope he said he won in a raffle. Weekend trips with his buddies that always seemed to cost just enough to drain whatever cushion we had left.
I never questioned it. I trusted him.
Until the hunting bag.
It was a Tuesday in early March. Dale was at work. I was cleaning out the hall closet because we were getting new carpet installed. His old camouflage duffel bag was stuffed in the back behind the Christmas decorations. I pulled it out to move it and the zipper was half open.
Inside, underneath a pair of insulated gloves and a blaze orange vest, there was a thick manila envelope.
I should have put it back.
Instead I opened it.
The first page was a life insurance policy from Southeastern Mutual Life & Casualty. $300,000. My full legal name — Sandra Kay Mercer — was printed clearly on the “insured” line. My signature was at the bottom of page 4.
Except I had never signed it.
I had never even seen this document.
I stared at the signature. It was close to mine. Close enough to pass a casual glance. But the way the “S” curled at the top was wrong. Dale had always been good at copying handwriting. He used to joke about it when he signed permission slips for the kids.
He wasn’t joking.
I turned to the second page and my whole kitchen went sideways. The sole beneficiary was not Dale. It was not our children. It was not my mother.
It was a woman named Kendra Nolan.
I didn’t recognize the name at first. But I recognized the address listed under hers — 4200 Commerce Park Drive, Suite 11. The same office park where Dale worked.
His secretary.
My hands went cold. I sat down right there on the hallway floor with the carpet samples scattered around me and read every single page. The policy had been active for 9 years. The premiums were $247 a month. Tucked between the pages was a stack of old bank statements with highlighted withdrawals that perfectly matched.
$247 every single month for 9 years. That was over $26,000. Pulled quietly and consistently from the same joint checking account I used to buy groceries, school supplies, and winter coats for our children.
He had been paying to insure my death and handing the payout to another woman.
I sat on that floor for 40 minutes. I didn’t cry. Something older and steadier took over. The kind of calm that only comes when the betrayal is so complete that anger hasn’t even caught up yet.
I photographed every single page with my phone. Both sides. The signature page. The beneficiary designation. The premium schedule. The bank statements. Then I put the envelope back exactly where I found it, zipped the bag, and pushed it behind the Christmas decorations.
That night I sat across from Dale at dinner and watched him eat the $4 rotisserie chicken I bought with the budget he had been quietly bleeding dry for nearly a decade.
“Good day?” he asked, not looking up from his phone.
“Quiet,” I said.
Emma asked for seconds. Jack fed a piece of chicken to the dog under the table. Dale scrolled through something on his screen and didn’t notice any of it.
I washed the dishes alone that night, and for the first time in 14 years, I looked at the back of his head while he watched TV and thought: you are a stranger.
The next morning, after I dropped the kids at school, I sat in the parking lot of the Walgreens on Bardstown Road and called Southeastern Mutual Life & Casualty.
I asked to speak to their fraud investigation department.
The woman who eventually called me back was named Mrs. Crane. She had a steady voice. She was calm, thorough, and methodical. And she did not seem surprised.
“Mrs. Mercer,” she said after I emailed her every photograph, “we’ve been monitoring this policy for 7 months.”
My chest tightened.
“You’ve been watching it?”
“Your husband made a significant amendment to the policy 6 weeks ago,” she said. “He added an accidental death rider. That doubles the payout to $600,000 in the event of death by accident. He forged your signature again on the amendment. Our system flagged it automatically.”
I couldn’t speak.
“Mrs. Mercer, I need to meet with you and your husband together,” she continued. “There is one question I need to ask him. In person.”
Mrs. Crane arrived at our house on a Thursday evening. She wore a dark blazer and carried a leather portfolio. Dale thought she was from the dealership’s corporate insurance audit. I had told him that to get him to agree to the meeting.
She sat in the living room across from both of us. She opened the portfolio, laid the policy on the coffee table, and looked directly at Dale.
“Mr. Mercer,” she said without a trace of emotion, “can you explain why you added a $300,000 accidental death rider to your wife’s policy 6 weeks ago — and why her signature on the amendment does not match a single verified sample in our system?”
Dale’s face went completely white.
His mouth opened but nothing came out.
Then Mrs. Crane said, “And can you explain why the beneficiary on this policy is not a family member, but a Ms. Kendra Nolan of 4200 Commerce Park Drive?”
Dale’s eyes shot to me. For the first time in 14 years, I saw real fear in them.
“Sandra—” he started.
“Don’t,” I said.
The front door opened behind us. Two federal agents from the insurance fraud task force stepped into the living room. Mrs. Crane had coordinated the entire thing. She had been building the case for months.
Dale was escorted out of our home in handcuffs at 7:14 PM on a Thursday, 20 minutes before Emma’s bedtime.
The investigation that followed was thorough and devastating. The forged signatures were confirmed by a federal handwriting analyst. Kendra Nolan was interviewed and admitted to a 6-year affair with Dale. She claimed she didn’t know about the insurance policy, but her bank records showed 3 separate deposits from Dale’s personal account totaling $14,000 — money he told me went toward truck repairs.
Dale was charged with insurance fraud, forgery, and criminal conspiracy. The accidental death rider triggered an additional investigation into whether he had been planning something far worse. His browsing history, which the FBI recovered from his work laptop, included searches for “hunting accident statistics,” “accidental discharge settlement,” and “life insurance payout timeline after spousal death.”
The judge denied bail.
My attorney, a woman named Ruth Abrams who had handled my sister’s custody case years earlier, filed for emergency divorce. The court froze all of Dale’s assets. Full custody of Emma and Jack was granted to me within 2 weeks.
Southeastern Mutual voided the policy entirely and issued me a formal letter of protection. Mrs. Crane called me personally the day the case was filed federally.
“Mrs. Mercer,” she said, “you saved your own life by opening that bag.”
Dale pleaded guilty to 3 counts of federal insurance fraud to avoid the conspiracy trial. He was sentenced to 4 years. Kendra Nolan was fired from the dealership and charged as an accessory.
I sold the house on Birchwood Lane. I used the equity to buy a smaller place closer to my mother’s. The kids adjusted slowly. Emma asked hard questions. Jack mostly wanted to know if Biscuit could still sleep in his room.
Last month I replaced the carpet that started all of this. The installer asked if I wanted the same color.
“No,” I said. “Something completely new.”